














What Is Liability Insurance? A Comprehensive Guide for Businesses
B
Business
LATEST NEWS
“What Is Liability Insurance? A Comprehensive Guide for Businesses”
Read more on
hindustanmetro.com
8 Oct 2026
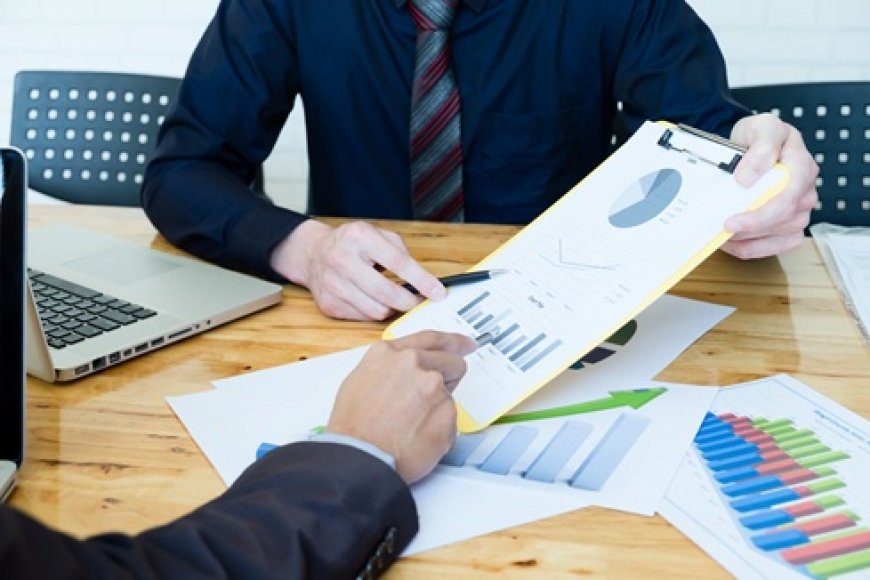
Running a business involves dealing with customers, suppliers, employees, and professional responsibilities. A business may also face allegations involving injury, property damage, or financial loss connected with its activities. Liability insurance can address certain legal liabilities, depending on the terms and conditions set out in the policy.
What Does Liability Insurance Cover for a Business?
Liability insurance is a broad term, and the risks you need to consider depend on what your business does, who you deal with, and the nature of your professional responsibilities.
Shivam Madaan
Shivam Madaan is the Founder and Editor of Hindustan Metro and Orvox News. Committed to unbiased and impactful journalism, he is dedicated to amplifying the voice of the people and delivering news that truly matters. His vision is to provide accurate, credible, and trustworthy information, ensuring journalism that informs, empowers, and serves the public interest