As India's borrowing costs come under renewed focus, financial resilience depends not just on the size of an EMI, but on how much income remains after every monthly commitment is paid.
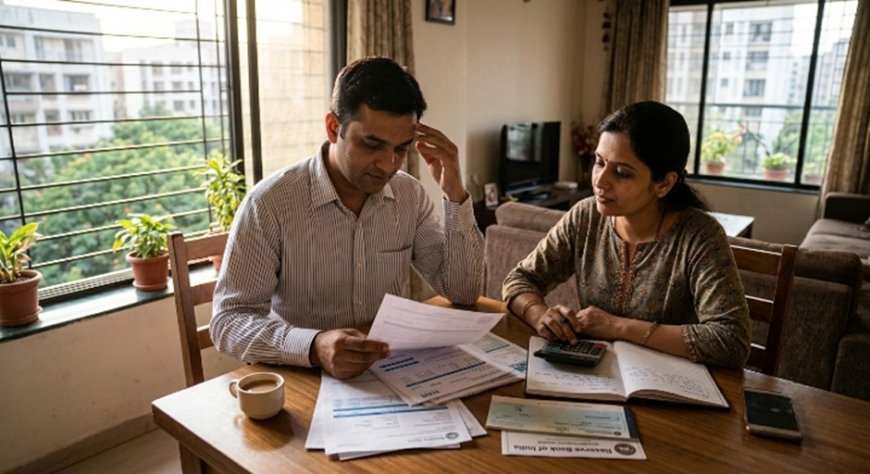
For many Indian households, an EMI is treated as a fixed part of life. Salary arrives, loan instalments are deducted, bills are paid, and the remaining amount covers everything else.
But this arrangement can become fragile when household expenses rise, income becomes uncertain or several loans begin competing for the same monthly salary.
With the Reserve Bank of India raising its repo rate to 5.50% in October 2026, borrowing costs have returned to the spotlight. The implications for individual borrowers will depend on their loan agreements and how lenders transmit policy-rate changes. Nevertheless, the development offers a timely reminder: a household's ability to manage debt can change even when its outstanding loan amount does not.
The Real Question Is Not Just Whether Your EMI Will Rise
When interest rates change, borrowers often focus on a single question: will my monthly instalment increase?
That is important, but it is not the only question worth asking.
Consider a salaried professional earning ₹80,000 a month, with ₹35,000 committed to loan repayments. After rent, groceries, transport, insurance and family expenses, the remaining amount may already be limited.
Even if the professional's existing EMIs do not change immediately, an unexpected medical bill or temporary income disruption could create a repayment problem.
Now consider a household managing a home loan, a personal loan and two credit card balances. Each obligation may appear manageable individually, but together they can leave little room for financial setbacks.
The pressure comes from the combined commitment, not necessarily from one particular interest rate.
This is why borrowers need to understand their overall repayment capacity instead of assessing every loan in isolation.
India's Borrowing Landscape Is Changing

The Reserve Bank of India's June 2026 Financial Stability Report placed household debt at 45.5% of GDP as of March 2026, above its reported five-year average of 42.9%. Non-housing retail loans accounted for 58.4% of household debt. These figures describe borrowing across households, not the proportion of families in financial distress.
At the same time, digital credit has expanded access to personal loans. A FACE report based on CRIF High Mark data found that digital NBFCs' outstanding personal-loan portfolio reached ₹1.54 trillion by June 2026, approximately 28% higher than a year earlier.
These developments do not mean that borrowing is inherently harmful. Credit can help households manage major purchases, emergencies and other financial needs.
The challenge arises when new borrowing is added to existing commitments without a clear understanding of the total repayment burden.
A loan that appears affordable at the time of approval may become difficult to manage after circumstances change. Financial resilience therefore requires more than qualifying for credit; it requires understanding what happens when income, expenses or repayment obligations change.
When Borrowers Start Looking for Another Loan
One common response to a monthly cash shortage is to borrow again.
A personal loan may be used to clear credit card dues. A credit card may then cover routine household expenses. Alternatively, a borrower may consider another loan to manage existing instalments.
Sometimes, refinancing or consolidation can help if the new arrangement genuinely reduces the overall cost or makes repayments more sustainable.
But borrowing again without examining the complete picture can simply move the problem from one account to another. The borrower may end up with additional fees, a longer repayment period or another fixed instalment.
Before taking on further debt, it is worth calculating total outstanding liabilities, combined monthly repayments, essential expenses and the amount realistically available for repayment.
The objective is not to avoid every form of borrowing. It is to understand whether the proposed decision improves the financial position or merely postpones the difficulty.
What If the Existing EMIs Are Already Unmanageable?
When repayments become difficult, delaying the decision can leave borrowers with fewer practical choices or less time to explore them.
The first step is to understand the actual shortfall. Is the problem temporary, caused by an unexpected expense, or does the household's income no longer support its existing repayment commitments?
The answer matters because different circumstances may call for different approaches.
Depending on the loan terms, lender policies and the borrower's financial position, options worth exploring may include revised repayment terms, restructuring, EMI reduction where feasible or negotiated settlement in appropriate cases.
These options are not interchangeable, and none is guaranteed. Restructuring or a revised EMI requires the lender's approval, while settlement can have implications for a borrower's credit history. Any proposed arrangement should be assessed against its costs, conditions and long-term consequences.
This is where informed decision-making becomes particularly important.
Why Debt Resolution Must Begin With the Borrower's Reality
AdvoExpert works with individuals and families facing repayment difficulties, helping them identify the right debt resolution approach for their circumstances and supporting them through the process.
Its approach includes examining the borrower's financial situation, discussing suitable routes and providing one-to-one support as clients navigate the chosen process. The objective is to help people understand not only what options may be available, but also what those options involve and what steps may follow.
A borrower with a stable income and a temporary cash-flow problem may need a different approach from someone whose income has fallen substantially. Treating both situations identically can overlook important differences in repayment capacity.
A transparent process should explain the potential benefits, limitations, costs and risks of the available options, while recognising that lenders retain control over their own decisions.
Financial Resilience Begins Before a Crisis
Interest rates, household expenses and income can change. A repayment plan that once seemed manageable may not remain so indefinitely.
Borrowers can improve their understanding of their financial position by reviewing all loan commitments together, monitoring available monthly cash flow, avoiding unnecessary additional borrowing and communicating with lenders when repayment difficulties emerge.
For those already facing repayment pressure, taking timely action can help them make more informed decisions. AdvoExpert works closely with borrowers to identify suitable debt resolution options based on their individual circumstances and supports them in putting those solutions into action, helping them work towards getting out of the debt trap with greater clarity and confidence.
Ultimately, the goal is not simply to keep paying EMIs month after month. It is to make financial commitments that remain manageable and to understand the available choices when circumstances change.
Because the real measure of a manageable loan is not just whether a borrower can pay this month's EMI. It is whether the entire repayment commitment makes sense for their financial reality.